Focused arrival windows
Useful updates and clear arrival timing.
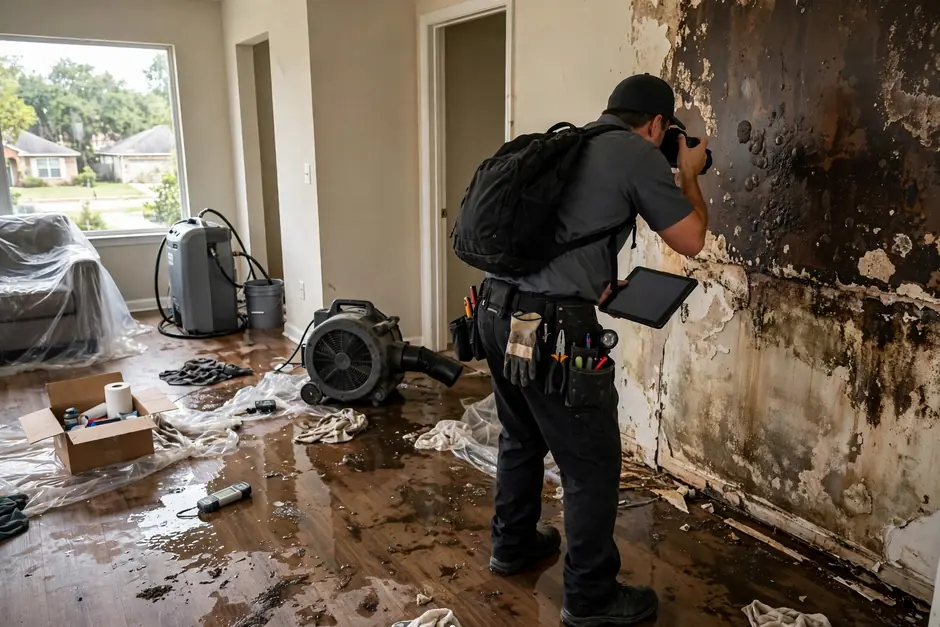
A water damage insurance claim Houston homeowners file usually starts in the worst possible conditions: the water is still standing, the rooms are wet, and the paperwork feels like the last thing anyone can face. This page is general information about how that process usually works — what to document, what the difference is between homeowners cover and flood insurance, and what an adjuster usually asks for. It is not insurance advice, and it does not promise what any policy covers or what any claim will pay. Restoration Enterprise documents the loss with photos and moisture readings, and shares that record with you and, with your permission, your adjuster. Call (346) 980-0009 any time — we are open 24 hours.
Useful updates and clear arrival timing.
Review the approach and scope before deciding.
Equipped vehicles and respectful cleanup.
Neighbors serving neighbors with follow-through.
We are a restoration company, not an insurer and not a public adjuster. What we do is document the loss properly and explain the general process, so you are not starting from nothing when you speak to your carrier.
Photos and video of the water, the waterline on walls, and damaged belongings, taken before anything is moved or removed. That record is the starting point for any claim.
Moisture readings logged from the first visit until materials reach dry standard, with the dates and rooms recorded. Adjusters commonly ask for this record.
A written list of damaged belongings and materials, room by room, so nothing is forgotten when the claim is filed.
A clear written scope of the extraction, drying and repair work, so the insurer can see what was done and why.
With your permission, we share the photos, readings and scope with your adjuster and answer questions about the work itself. We do not negotiate your claim or speak for you.
Plain-language general information about the steps that usually follow a water loss — notifying the insurer promptly, mitigating further damage, and keeping receipts — so you know what to expect.
Share what is happening and receive a clear next step from the local team.
A water damage insurance claim Houston homeowners file follows a pattern that is mostly the same from one carrier to the next, even though the details of each policy differ. First the loss is discovered and the water is stopped. Then the damage is documented — photos, video, moisture readings and an inventory — before anything is moved or thrown away. Then the insurer is notified, the loss is mitigated so it does not get worse, and an adjuster reviews the documentation and the scope of the work. The adjuster decides what the policy covers; the restoration company documents what happened and what was done.
Two distinctions matter more than any other. The first is sudden versus gradual: in general terms, a standard homeowners policy usually covers sudden and accidental water damage such as a burst pipe, while gradual leaks and wear-and-tear damage are usually excluded. The second is water damage versus flood: flood is excluded from a standard homeowners policy and needs separate flood insurance, typically through the National Flood Insurance Program or a private flood policy. A burst pipe and a bayou flood are different losses under most policies, even when the water in the room looks the same. For the work itself, the chain is the same as any water loss: emergency water extraction removes the standing water, structural drying brings the structure back to dry standard, and mold remediation is arranged where the water sat long enough for mold to establish. The water damage restoration page describes that sequence, and the flood damage cleanup page covers rising water in detail.
Scope boundary: we do not act as a public adjuster, we do not promise coverage or a claim outcome, and we do not waive or cover deductibles. Public adjusting is a separately licensed activity in Texas. What we do is document the loss, explain the general process, and share the documentation with your adjuster with your permission.
On the first visit we photograph and video the water and the damage before anything is moved, and we take moisture readings across the affected rooms. That record is started on day one, not reconstructed later.
Standing water is extracted and the structure is dried, with readings logged in writing. The drying record shows what was wet, what was dried and when it reached dry standard.
Damaged belongings and materials are listed room by room, and a written scope of the extraction, drying and repair work is prepared. You receive a copy of everything.
With your permission, we share the photos, readings, inventory and scope with your adjuster and answer questions about the work itself. We do not negotiate the claim or speak for you.
Once the structure is dry, the damaged materials are repaired as scoped, and the final moisture report and photos are added to the record. You keep the full file.
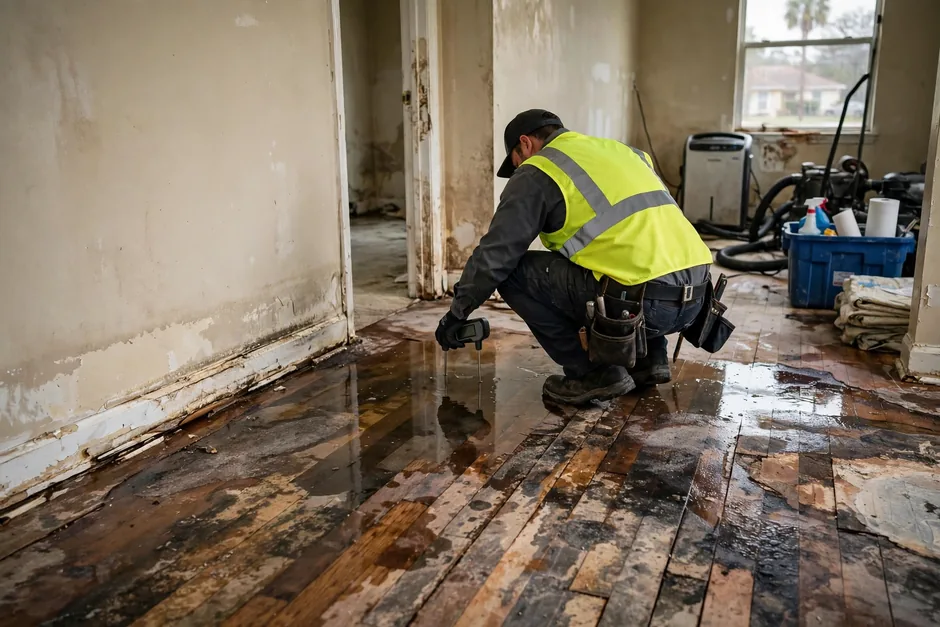
Photos and video of the water, the waterline and damaged belongings, taken before anything is moved or removed.
Measures moisture content in wood, drywall and air, logged in writing from the first visit until materials reach dry standard.
Finds hidden water behind drywall and under flooring that the visible damage does not show, so the record covers the full loss.
Room-by-room lists of damaged belongings and materials, so nothing is forgotten when the claim is filed.
A clear written scope of the extraction, drying and repair work, so the insurer can see what was done and why.
Lets us look inside wall and ceiling cavities to confirm hidden water and record it for the file.
Daily moisture readings recorded in writing, showing the dry-down over time rather than a single snapshot.
Before, during and after photos of the repair work, so the file shows the full sequence from loss to finished room.
You receive the photos, readings, inventory and scope, so the record is yours whether you speak to the adjuster yourself or ask us to share it.
ANSI/IICRC S500 is the published industry standard for water damage restoration, covering water categories, drying goals and documentation. It is an industry standard, not law, and we describe our work against it rather than claiming certification to it.
We document the water before anything is moved, extract it, dry the structure, and share the photos, readings and scope with the adjuster with the homeowner’s permission. The record is complete from day one.
Our photos and moisture readings show what was wet and when, and the written scope separates the interior water damage from the roof repair. What the policy covers is the insurer’s decision; the record is ours to provide.
We document the floodline, the water and the damaged materials, and the record is kept for the flood claim, which follows the flood policy and its own deadlines rather than the homeowners policy.
We map the full wet zone, log the readings, and prepare an inventory and scope that show the extent of the loss. Gradual damage is a coverage question for the insurer; the documentation shows what happened.
Houston water losses raise the same claim questions again and again: was it sudden or gradual, was it flood or water damage, and what does the record show? The answers depend on the policy, but the documentation that supports any answer is the same in every neighborhood.
Homes beside Brays Bayou where flood and homeowners claims often run side by side, and where the flood-versus-water distinction matters most.
Homes beside Lake Houston where slow rain and reservoir levels shape the loss, and where the record needs to show the water’s path.
Homes near the bay where storm surge and flooding raise flood-insurance questions that a homeowners policy does not answer.
Homes beside Buffalo Bayou and the reservoirs, where the claim record needs to show what the water did and when.
Apartment buildings where a single loss can involve a landlord, a tenant and a property manager, and where the documentation has to serve all three.
Older homes where a slow roof leak raises the sudden-versus-gradual question, and where the attic record decides it.
High-rise and commercial losses where the claim may involve a building owner, a tenant and a management company at once.
In general terms, sudden and accidental water damage is usually covered, while gradual leaks and wear-and-tear damage are usually excluded. The record shows which one it was.
Flood is excluded from a standard homeowners policy and needs separate flood insurance. A burst pipe and a bayou flood are different losses under most policies.
A supply line burst overnight and flooded a kitchen and hallway. The homeowner had never filed a claim and did not know what the insurer would ask for.
We photographed the water before anything was moved, logged moisture readings from the first visit, prepared an inventory and a written scope, and shared the file with the adjuster with the homeowner’s permission. The homeowner kept a full copy.
Maintenance: We recommended keeping the photos, readings and scope together in one file, and keeping receipts for any emergency spending alongside them.
A roof leak stained a bedroom ceiling and the insurer asked whether the damage was sudden or gradual. The stain alone could not answer that.
Our attic photos and moisture readings showed what was wet and when, and the written scope separated the interior water damage from the roof repair. The record answered the factual questions; the coverage decision stayed with the insurer.
Maintenance: We suggested a roof check before storm season and a look in the attic after heavy rain, so any future leak is documented from the start.
Bayou water entered a ground floor and the homeowner held separate flood insurance. The flood claim followed the flood policy, not the homeowners policy.
We documented the floodline, the water and the damaged materials, and the record was kept for the flood claim with its own deadlines. Nothing was discarded before the adjuster had seen it.
Maintenance: We suggested checking the flood policy’s deadlines directly with the insurer, since flood deadlines differ from homeowners deadlines.
Most claim trouble comes from the record, not the loss. Here is what we prepare so the record is complete.
Cleanup starts before anyone photographs the water. We photograph and video the loss before anything is moved, on the first visit.
An adjuster asks for readings and there are none. We log readings in writing from day one until materials reach dry standard.
Damaged belongings are thrown away before they are listed. We prepare a room-by-room inventory before anything is discarded.
A flood loss is filed under a homeowners policy, or the reverse. We explain the distinction in general terms and keep the record for the right policy.
The insurer cannot see what was done or why. We prepare a written scope of the extraction, drying and repair work for every job.
A claim is decided on the record, and the record is made on day one. Our work is built around documenting the loss properly — photos before cleanup, readings in writing, an inventory, and a written scope — and sharing that record with you and, with your permission, your adjuster.
Dealing with water damage is stressful, but Restoration Enterprise made the whole situation manageable. They were calm, knowledgeable, and reassuring from start to finish. I could finally breathe knowing my home was in good hands.
Exceptional Service Beyond Expectations! I am delighted to write this review for the highly professional and efficient water restoration company that turned our disaster into a blessing. When we discovered a serious plumbing issue in our kitchen, we were overwhelmed with anxiety and worry. However, the moment we reached out to them, they swiftly stepped in, assuaging our fears and promptly handling the situation. The thing that struck me the most about this company was their extraordinary customer service. They were not just professional, but also empathetic, understanding the stress we were under. They were quick to respond, arriving at our home within an hour of our call, fully equipped to deal with the situation. The cleanup process was swift and unobtrusive, causing minimal disruption to our daily routine. They even liaised with our insurance company, alleviating us from the added stress of handling paperwork. It's not often that you encounter a company so dedicated to their work and to the satisfaction of their clients. They turned an unfortunate event into a surprisingly positive experience. We are beyond pleased with the results and are grateful to have our kitchen back, in even better shape than before! If you are ever unfortunate enough to encounter a water disaster in your home, I wholeheartedly recommend this water restoration company. Their professionalism, efficiency, and dedication to customer satisfaction are second to none.
Across all 152 Google reviews, Restoration Enterprise holds a 4.7-star average: 142 five-star reviews and 10 one-star reviews. That aggregate rating is the full picture — the two reviews shown here are the only individual reviews quoted on this site.
In general terms, a standard homeowners policy usually covers sudden and accidental water damage such as a burst pipe, while gradual leaks and wear-and-tear damage are usually excluded. Flood is excluded from a standard homeowners policy and needs separate flood insurance. What a specific policy covers depends on that policy, so check with your insurer. This page is general information, not insurance advice.
A homeowners claim covers water damage under a homeowners policy, while a flood claim is filed under a separate flood insurance policy, typically through the National Flood Insurance Program or a private flood policy. The two policies have different coverage and different deadlines. In general terms, a flood policy usually requires proof of loss within 60 days of the loss — check your own policy and your insurer’s guidance for the deadlines that apply to you.
Photograph and video the water itself, the waterline on the walls, and every damaged belonging and material, before anything is moved or removed. Photograph each room, the source of the water where it is visible, and the readings on any moisture meter. Do not discard damaged items until the adjuster has seen them or the insurer agrees.
No. We document the loss and explain the general process, and with your permission we share the photos, readings, inventory and scope with your adjuster and answer questions about the work itself. We do not negotiate your claim, promise coverage or a claim outcome, act as a public adjuster, or waive or cover deductibles. Public adjusting is a separately licensed activity in Texas.
A denial is a decision by your insurer, and we cannot promise an appeal outcome or give legal advice. In general terms, you can ask the insurer for the reasons in writing, review the policy language they cite, and consider speaking to the Texas Department of Insurance or a lawyer. What we can do is make sure the documentation of the loss is complete, so you have the full record to work from.
Not seeing your question? Our local team can help you understand urgency, scheduling and what to expect.
Ask the local team
The restoration itself — extraction, drying and repair — is what the documentation describes. The flagship page covers the full sequence.
View service
Extraction is also mitigation: removing standing water promptly is part of what most policies expect after a loss.
View service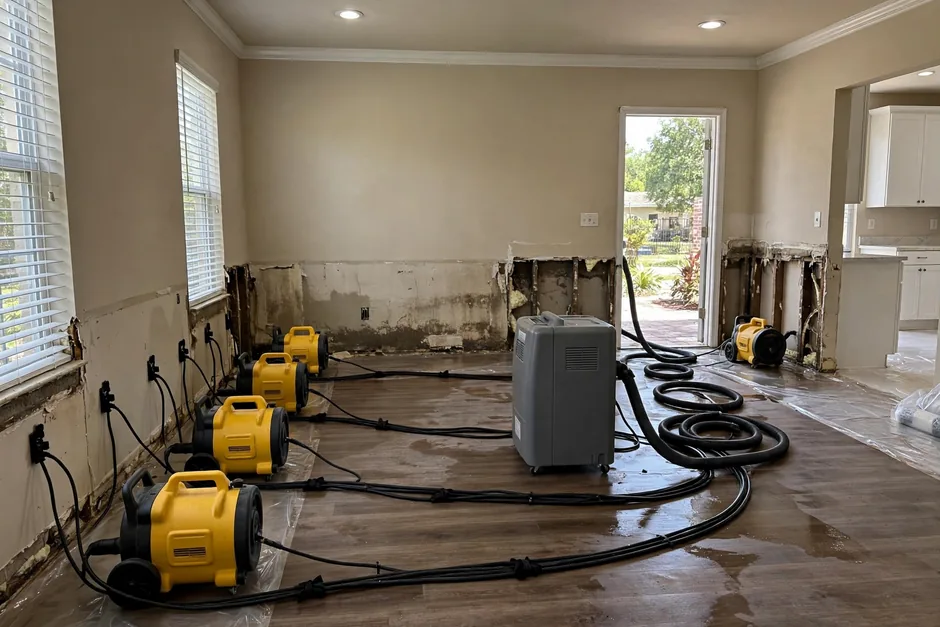
The drying log — readings in writing until materials reach dry standard — is one of the documents adjusters most commonly ask for.
View service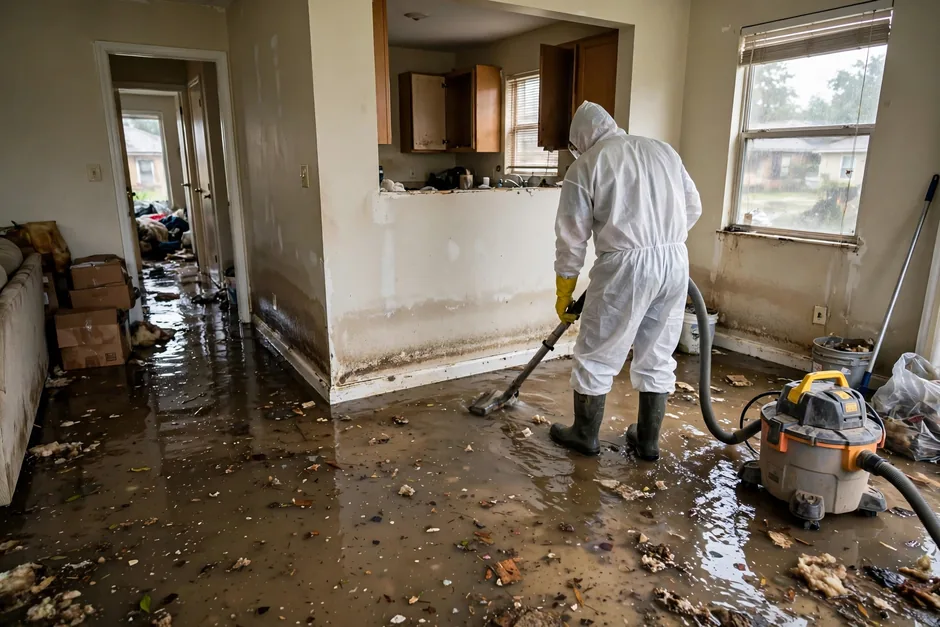
Rising bayou and street water is a flood loss, not a homeowners water-damage loss, and it is documented for the flood policy.
View serviceWe answer the phone around the clock, including weekends and holidays. Tell us what happened and where you are, and we will give you a clear next step. Phone is our contact channel.